Global Credit Trends
Explore global credit and financial data insights. Delivering trends in credit risk, debt, utilization and delinquencies from around the world.
Top Trends and Highlights
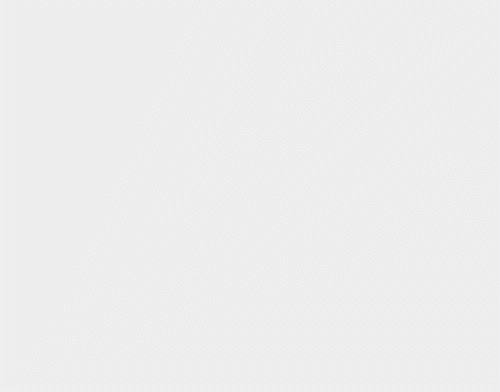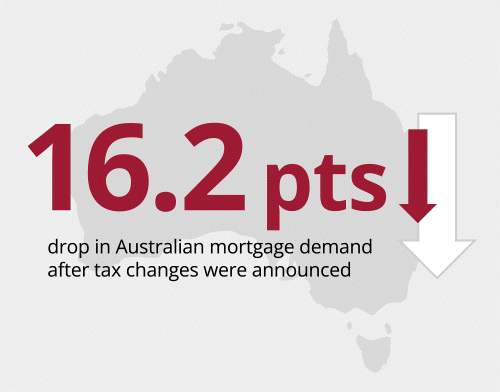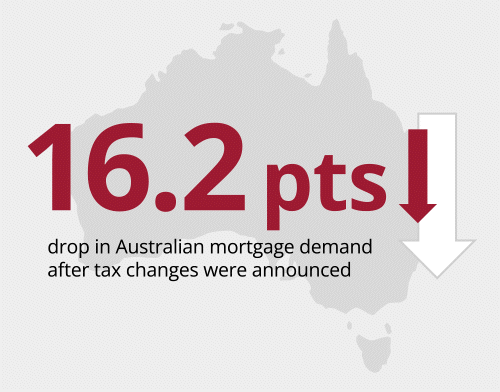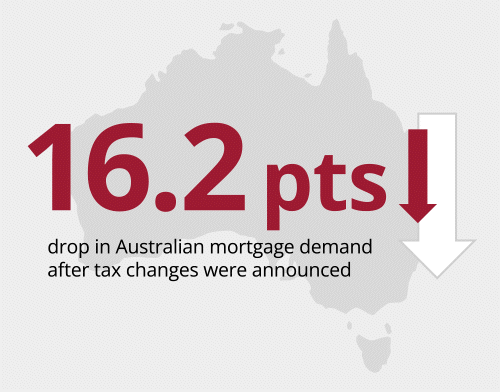
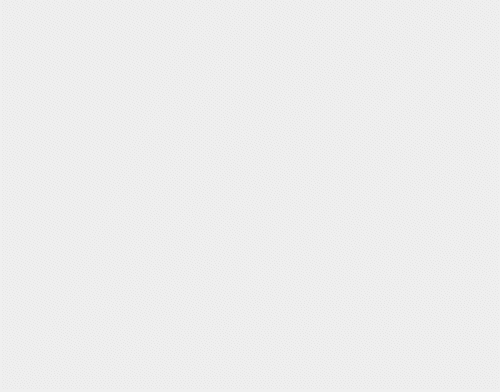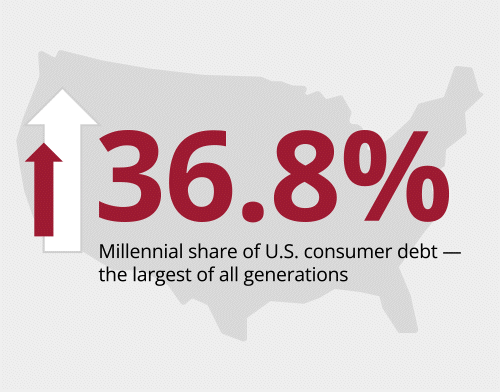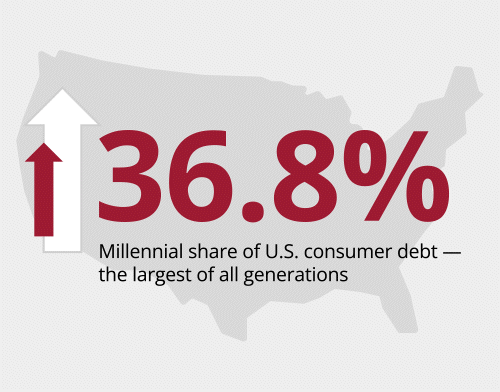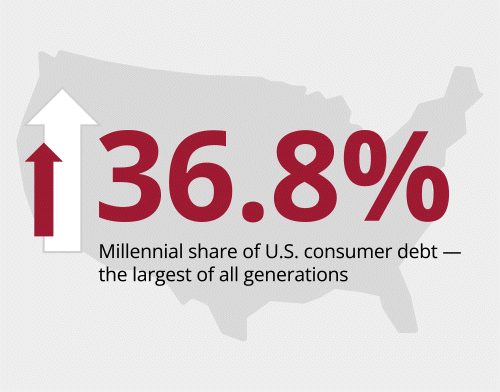
The Equifax First-Half 2026 Global Credit Trends report shows Australian mortgage demand swinging 16.2 percentage points after May 2026 tax reform, from 3.7% growth to a 12.5% contraction. In the United Kingdom, 29% of Buy Now Pay Later users aged 18 to 24 made no other traditional credit repayments in 2025 as BNPL entered FCA regulation. Millennials became the largest debt-holding generation in the United States, reaching 36.8% of total U.S. consumer debt by May 2026.
 Mortgage Debt
 United States: In Q1’26 mortgage debt continued the upward trajectory from the prior year to $13.2T before dipping 2.5% YoY in Q2’26.
Canada: Mortgage debt maintained a steady upward climb in Q2’26, rising 1.04% quarter-over-quarter and 3.96% YoY.
Australia: A decline in mortgage applications has yet to impact overall portfolio size. Total value of mortgage credit limits grew by 7.2% year-on-year in Q2’26.
Brazil: In Q2’26, credit expansion remained robust, with total consumer credit and household lending growing by 8.5–9.2% YoY. Non-mortgage origination (credit cards, auto, and personal loans) surged 11.8% YoY, continuing to drive market growth and representing the majority of total household debt.
India: Overall portfolio debt grew by 10% compared to last year.
 Non-Mortgage Debt
United States: U.S. non-mortgage debt remained mostly flat during 1H’26, rising 1.2% from Q1’26 to Q2’26.
Canada: Following a drop in non-mortgage debt in Q1’26, balances saw a seasonal rebound in the second quarter. Non-mortgage debt reached $712.2B in Q2’26, marking a 4.8% jump YoY and a 2.09% increase from Q1’26.
United Kingdom: The long term increasing trend in credit card balances continued into 2026, demonstrating the strong demand and supply in the market. Total credit card debt is now 18.5% above pre-pandemic levels.
Argentina: During 1H’26, debt levels rose by 5.8% vs 2H’25 and 22.8% vs 1H’25.
Spain: Spain’s debt profile in 1H’26 is characterized by a strong, continued deleveraging of the private sector (both households and corporations) paired with high but gradually consolidating public debt. Robust nominal GDP growth and lower interest rates have helped keep financial debt burdens well below Eurozone averages.
Debt: Money borrowed by consumers at a point in time. Refers to amortized limit or outstanding balance depending on data collected from each region, except Spain which reports just defaulted assets because the Spanish Bureau manages negative data only.
Non-Mortgage: Includes Buy Now Pay Later, credit cards, installment loans, personal loans and automobile loans. Availability and coverage will vary by region.
 North America
 North America
 Canada: Consumer credit demand softened in the first half of 2026, with non-mortgage inquiries dropping below 1H’25 levels. Auto demand remained sluggish compared to 1H’25, dropping by 9%.
This overall contraction highlights a widespread reluctance among Canadians to finance big-ticket items. While rising delinquency levels have started to slow, isolated pockets of financial strain continue to grow in some areas.
 South America
 South America
Argentina: Demand declined during 1H’26, dropping 22.4% versus 2H’25 and 36% against 1H’25 (YoY).
Ecuador: Credit demand showed positive growth during 2026, supported by strong demand for business working capital and personal loans.
Brazil: Credit demand showed a mild seasonal rebound in Q2’26 — reaching 38.6 million applications (+5.1% QoQ) — as the Central Bank brought the Selic rate down to 14.25%. Lenders remained selective due to high household debt and overall 30+ DPD delinquency stabilizing at 7.00%.
 Europe
 Europe
Spain: Domestic demand stood out as the main growth engine for Spain in 1H’26. Resilient private spending — backed by steady job creation, real wage gains, and lower borrowing costs — effectively offset softer net external demand.
 Oceania & Asia
 Oceania & Asia
Australia: Mortgage demand and inquiries fell 9% YoY in Q2’26, reversing previous growth trends. This downturn follows announced tax reforms abolishing most negative gearing and capital gains tax benefits for investors.
New Zealand: Growth in mortgage inquiries driven by a competitive market and borrower churn has tempered in 1H’26 but volumes remain elevated (+10.5% vs. 1H’25). Personal loans also saw 4.9% YoY growth, while credit cards fell 2.6%.
India: Demand for gold loans continued to increase, growing at a similar rate to the previous half-year.
 Card Utilization
 United States: U.S. credit card utilization remained flat to just above 20% to begin the year and through 1H’26.
Canada: After a slow start to the year in consumer card usage, credit card balances and utilization grew in the second quarter, supported by a seasonal rise in consumer spending.
Argentina: Credit card utilization remains stable during 1H’26, around a ratio of 25.4%.
Ecuador: Credit card utilization remains stable, supported by steady debt and limits.
India: Credit cards continue to decline resulting in both lower acquisitions and also lower limits on new acquisitions.
 Card Delinquency
United States: U.S. credit card 90+ delinquencies remained flat to begin the year at 1.86% before dipping to 1.65% in Q2’26. The Q2 rate was marginally higher than the comparable Q2’25 time period of 1.55%.
Canada: The overall 90+ ($) delinquency rate for credit cards improved slightly to 4.19% in Q2’26, down from 4.28% in the previous quarter, but still remained higher than 2025, showing a 6.8% annual increase.
Brazil: Credit card interest rates, particularly for revolving credit, remained at extremely elevated levels through Q2’26. According to Central Bank data, average revolving credit rates stayed above 400% annually, despite the initial reduction in the Selic rate to 14.25%. Coupled with a 44.50% limit utilization rate, these conditions continued to constrain borrowers' repayment capacity, sustaining pressure on household finances and keeping delinquency levels under close monitoring.
Australia: General card delinquency rates remain stable despite challenging environments. While the 90+ day delinquency rate for credit cards remained unchanged, the total value of delinquent balances increased by 3.4% YoY.
 North America
 North America
 United States: Mortgage delinquencies ticked higher to 0.99% in Q1’26 before leveling to 0.94% in Q2’26, both notably higher compared to corresponding YoY time periods (0.81% in Q1’25 and 0.72% in Q2’25). Installment Loan delinquency rates began the year at 2.15% before sliding to 1.99% in Q2’26.
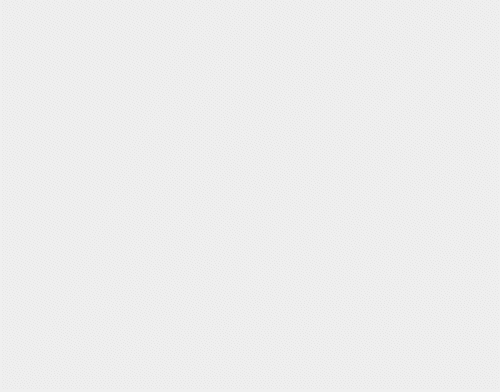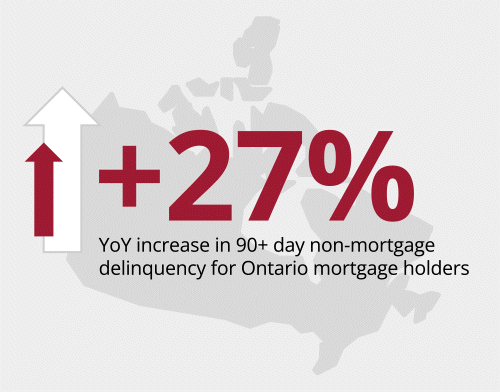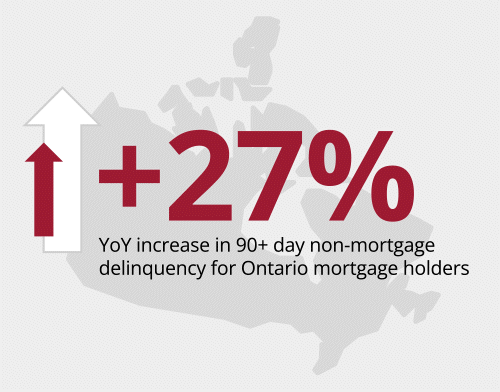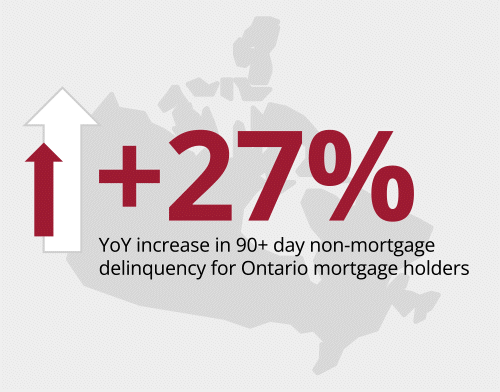
Canada: National non-mortgage delinquency rates saw a seasonal improvement from the previous quarter, but remain persistently elevated YoY. This ongoing financial strain is widely felt, with approximately 1 in 21 Canadians missing a credit payment during 2Q’26.
 South America
 South America
Argentina: Delinquency rates kept rising, hitting 15% in Q2’26, almost doubling the Q2’25 rate.
Ecuador: Delinquency remained stable overall, mitigating flat real incomes with collection strategies and provisioning.
Brazil: By Q2’26, overall delinquency (30+) showed signs of stabilization at 7%, easing slightly from Q1’26 peaks (7.28%) as the Central Bank started Selic rate cuts (down to 14.25%). Despite a resilient labor market, high household leverage and credit usage continue to weigh on repayment capacity.
 Europe
 Europe
United Kingdom: While credit metrics stabilized through late 2025, delinquency rates across unsecured markets have recently edged upward. This emerging trend highlights how cumulative debt burdens continue to squeeze household liquidity despite broader economic recovery.
 Oceania & Asia
 Oceania & Asia
Australia: While mortgage and personal loan delinquency rates by accounts remain stable, the total value of delinquent balances for these accounts rose significantly, increasing by 7.5% and 14.1% respectively.
New Zealand: Mortgage delinquencies remained broadly stable at 0.29% through 1H’26. Meanwhile, non-mortgage delinquencies saw varying levels of improvement, led by auto loans (-26 bps), personal loans (-5 bps), and credit cards (-2 bps).
India: Mortgage delinquencies improved by 18bps in Q2’26 compared to Q2’25.
Delinquency: The delinquency rate refers to the percentage of loans that are 90 or more days past due.